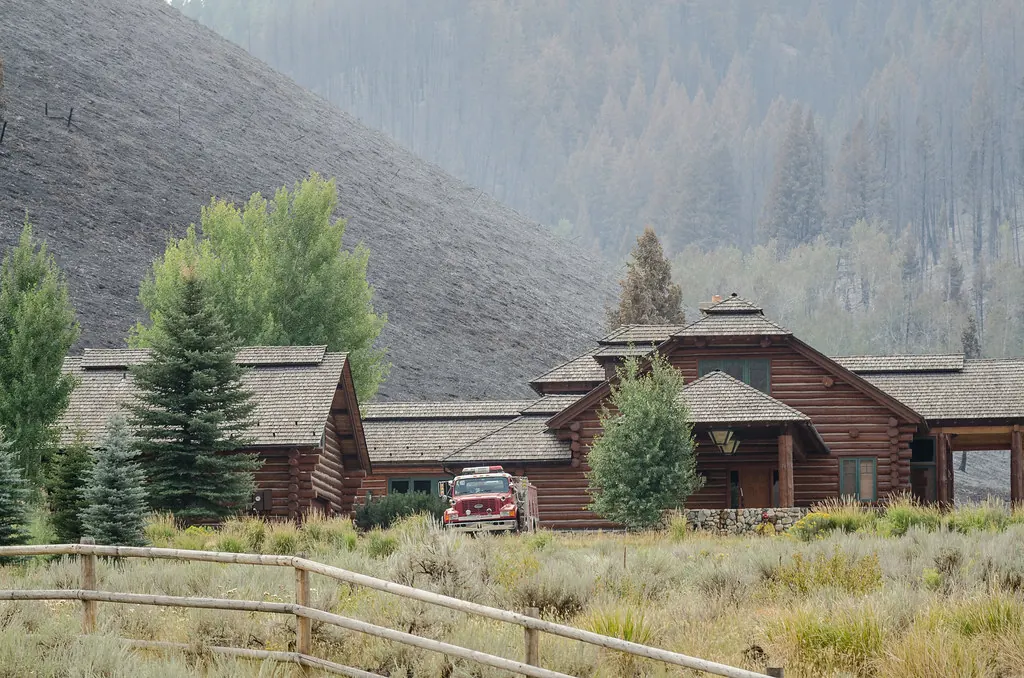
Wildfire in Wyoming
Large fires have become a regular part of Wyoming summers. The 2020 Mullen Fire burned well over 150,000 acres in the Medicine Bow National Forest and destroyed dozens of cabins and structures near the Colorado line. Grass fires on the eastern plains move fast in high wind, and beetle-killed timber across the southern and western mountains adds fuel near subdivisions and recreation cabins.
Three kinds of wildfire claims
- Total losses. The question is the real cost to rebuild — often far from town, with limited contractor availability, long material hauls and new code or defensible-space requirements.
- Partial burns and ember damage. Decks, siding, vents, roofs and outbuildings scorched or melted while the main structure survived.
- Smoke and ash. Homes that never burned but sat in heavy smoke for days: HVAC systems, insulation, soft goods and finishes that need cleaning or replacement.
What we document
We photograph and measure every structure, including the barns, sheds, fencing, well houses and corrals that are easy to miss. For smoke claims, we coordinate with industrial hygienists or restoration contractors when testing is needed so the panel has objective evidence, not opinion.
Policy limits and extended coverage
Wildfire total losses often reveal that dwelling limits were set years ago. An appraisal panel values the loss, but what is paid is capped by your limits and any extended replacement cost endorsement. We will show you the gap between the two so you understand where you stand.
Questions about wildfire, ember & smoke appraisal
Is smoke damage covered if my house didn’t burn?
Many policies cover sudden smoke damage from a nearby fire. The extent of cleaning or replacement is a valuation question a panel can decide.
How do rural rebuilding costs get priced?
We price from actual contractor rates, material delivery and mobilization to your location rather than using town averages.
Are outbuildings and fences included?
If they are covered under your policy, yes. Each one is documented and valued separately.