Where Wyoming home estimates usually fall short
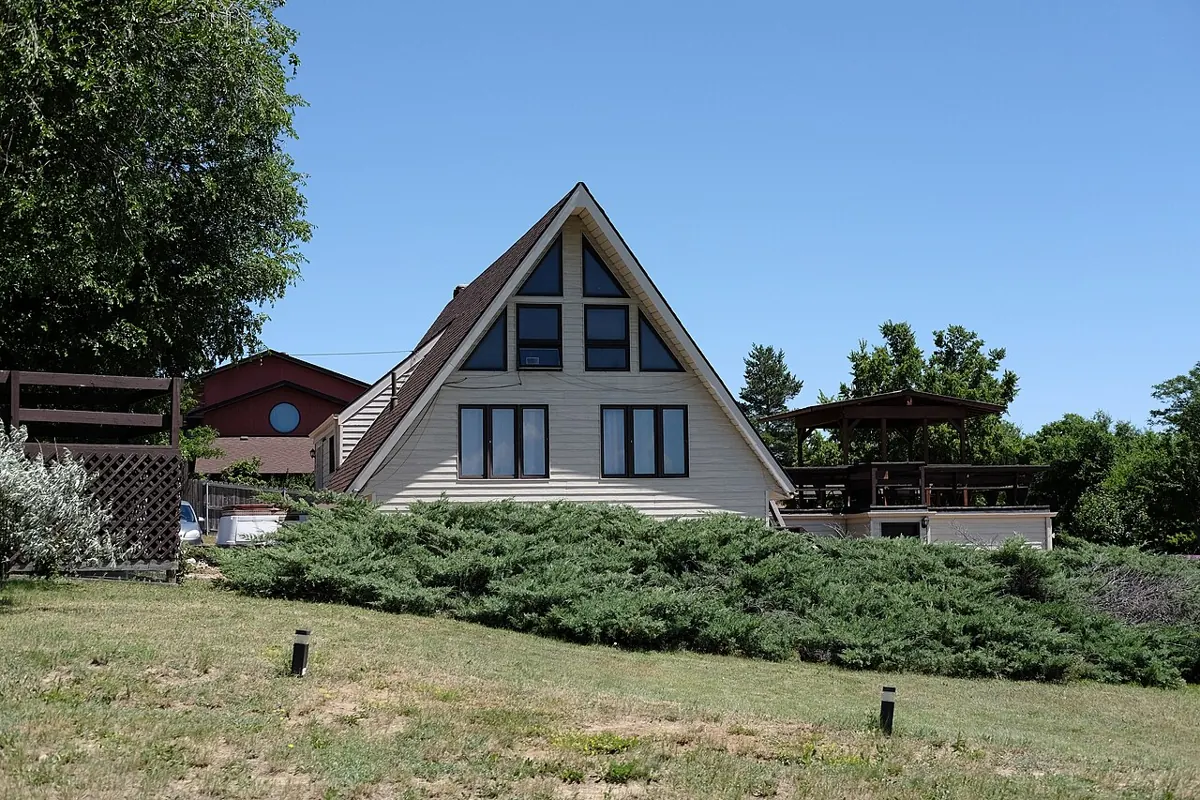
Wyoming’s housing stock is wider than most people expect: brick bungalows in Cheyenne’s older neighborhoods, 1970s energy-boom ranches and split-levels in Casper and Gillette, manufactured and modular homes on acreage outside nearly every town, and timber-frame houses in Teton and Park counties that cost several times the state average to rebuild. A generic estimate template handles none of them well.
- Partial-slope roof approvals when hail hit every exposed facet, or when the remaining shingles cannot be matched.
- Siding on one elevation only, even though the manufacturer discontinued the profile and the house will end up two colors.
- Detached garages, shops and fences left off the first inspection entirely.
- Interior water losses priced as “dry and paint” without the baseboard, insulation or flooring that was actually wet.
- Remote-location costs — mileage, lodging, crane or lift time — that a desk adjuster’s price list never includes.
How homeowner claim appraisal works with us
We start with a free conversation and a look at your declarations page, the carrier’s estimate and your photos. If the numbers support it, we inspect the property, write our own line-item estimate and tell you plainly what a panel is likely to accept. If appraisal is invoked, we serve as your appraiser through the award. If the gap is small, we will tell you that a documented supplement request is probably faster and cheaper.
Manufactured and modular homes
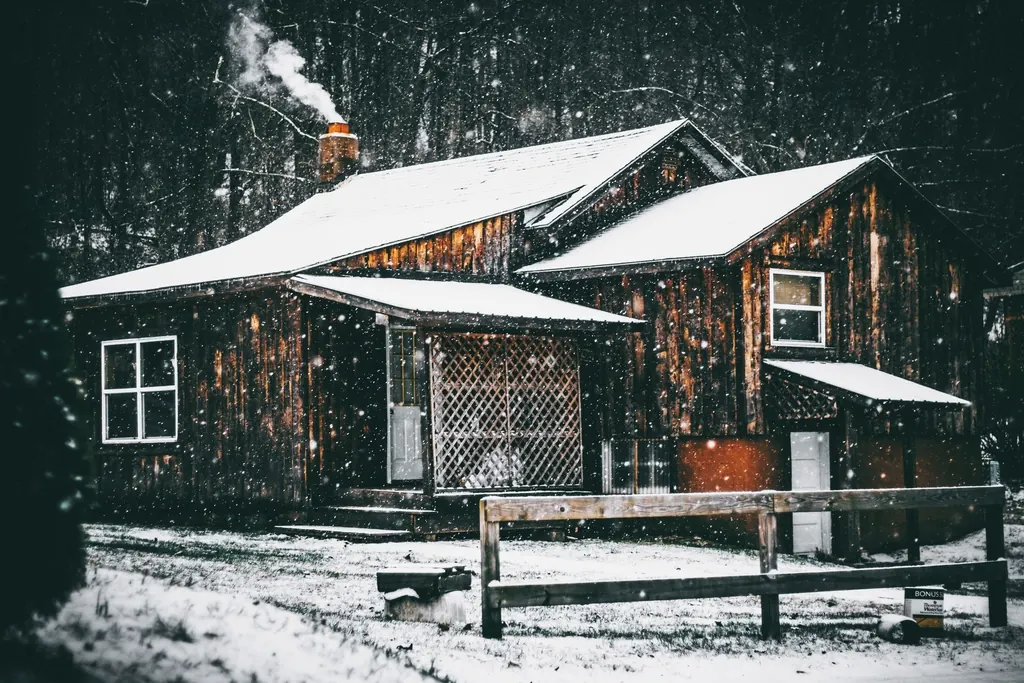
Manufactured homes are common across rural Wyoming, and their claims have quirks: metal or composition roofs with unusual profiles, skirting and tie-downs, and replacement parts that may only be available from the original manufacturer. We price those items from real supplier data rather than site-built equivalents.
Cabins and second homes
Vacant-season losses — a pipe that freezes in January at a cabin on Casper Mountain or above Centennial — raise questions about notice and heat maintenance that are coverage issues, not appraisal issues. We help you sort out which is which before money is spent on a panel.
Questions about homeowner claim appraisal
Do you handle contents as well as the building?
Yes. Contents disputes usually turn on replacement prices, depreciation and missing items. We build a priced inventory and compare it with the carrier’s, line by line.
Is my detached shop covered the same way as my house?
Usually it falls under Other Structures coverage, which has its own limit. The appraisal panel values the damage; your policy limits cap what is paid.
Can you help if my home is a manufactured home?
Yes. We appraise manufactured and modular home losses and price their materials from manufacturer and supplier sources.